Renewable Energy
Cover for developers, contractors, and operators of renewable energy assets, from construction through decades of operation.
Each technology has its own risk profile.
Solar PV plants and rooftops
Large solar plants hold high values in panels, inverters, and transformers spread over wide areas. Dust, heat, and sandstorms are constant operating conditions in the region.
- Damage to panels from storms and accidents
- Inverter and transformer breakdown
- Theft of cabling and components
- Lost revenue while equipment is repaired
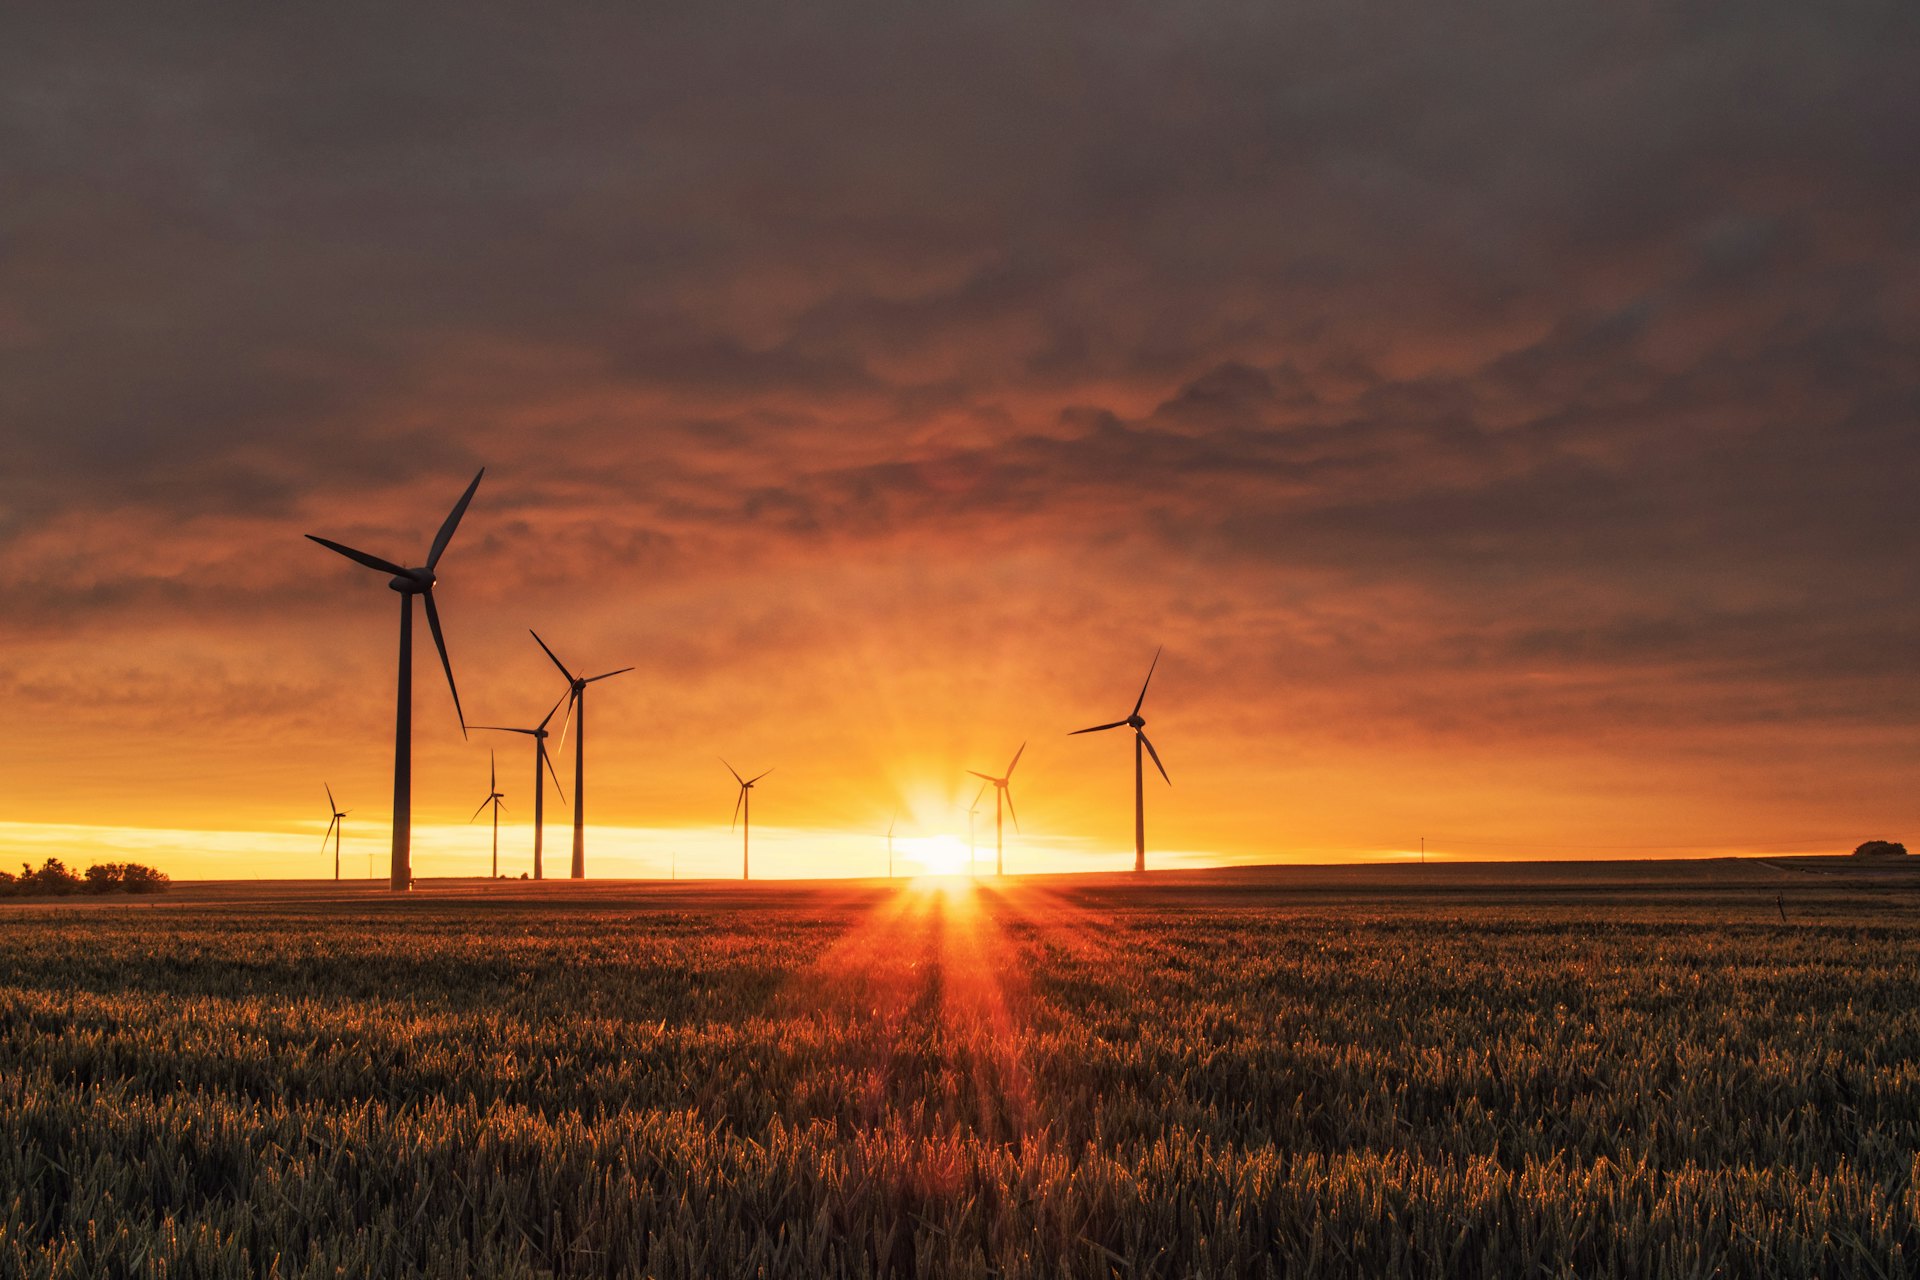
Wind turbines
Turbines concentrate value in a small number of components, and replacing a gearbox or blade can take months because of crane and parts availability.
- Mechanical and electrical breakdown
- Lightning and storm damage
- Crane and transport risks during installation
- Extended business interruption periods
Battery energy storage
Battery systems bring fire and thermal runaway risks that insurers assess closely, including spacing, detection, and suppression systems.
- Fire and explosion
- Equipment breakdown and degradation
- Third-party liability for neighbouring sites
- Business interruption
Cover across the asset's life.
Construction all risks
Damage to the works during construction, testing, and commissioning.
Operational all risks
Physical damage and machinery breakdown once the plant is running.
Revenue protection
Lost generation income after insured damage stops the plant.
Liability
Third-party injury and property damage claims at every stage.
Insurance that satisfies project finance.
Renewable projects are usually financed, and lenders set detailed insurance requirements.
- 01
Review requirements
We read the insurance schedule in the finance documents.
- 02
Structure cover
Limits, deductibles, and endorsements are set to meet lender terms.
- 03
Endorse to lenders
Lenders are named as loss payees and co-insureds where required.
- 04
Report and renew
We provide the confirmations lenders need at each renewal.
Is weather-related underperformance insured?
Standard property policies cover physical damage, not low sun or wind. Specialist parametric covers exist for some weather risks.
Do you cover rooftop solar on commercial buildings?
Yes, usually by adding the installation to the building's property policy or arranging a separate equipment policy.
Can lenders be named on the policy?
Yes. We arrange loss payee and co-insured endorsements to meet finance requirements.
What do insurers look for in battery storage?
Fire detection and suppression, separation distances, monitoring systems, and the manufacturer's track record.
Need protection for your future?
Global coverage, trusted assurance. Our advisors are available Mon – Sun 9:00 AM – 6:00 PM.